Most people think of Section 8 as help with rent. But if you already have a voucher, you may be able to use it to buy a home instead. Under the Housing Choice Voucher Homeownership Program, families can put their monthly voucher help toward a mortgage instead of a landlord's rent.
Here is how it works, who can use it, and how to get started.
Get instant answers to your housing questions.Chat Now
What Is the Section 8 Homeownership Voucher Program?
The program lets families who already have a Housing Choice Voucher use it to buy a home. Instead of your housing authority sending money to a landlord, the money helps cover your monthly homeownership costs.
There is one big catch. Not every housing authority offers this program. Each one decides for itself, so the first step is to find out whether your local office does. If yours doesn't, HUD encourages residents to ask their housing authority to start one.
Who Can Qualify?
Rules differ a little from place to place, but the basics come from the federal government. You will usually need to:
- Already have a Housing Choice Voucher. The program is only open to families in the voucher program.
- Be a first-time homeowner. This generally means no one in your household has owned a home in the past three years. A single parent or displaced homemaker who owned a home with a spouse still counts as a first-time buyer.
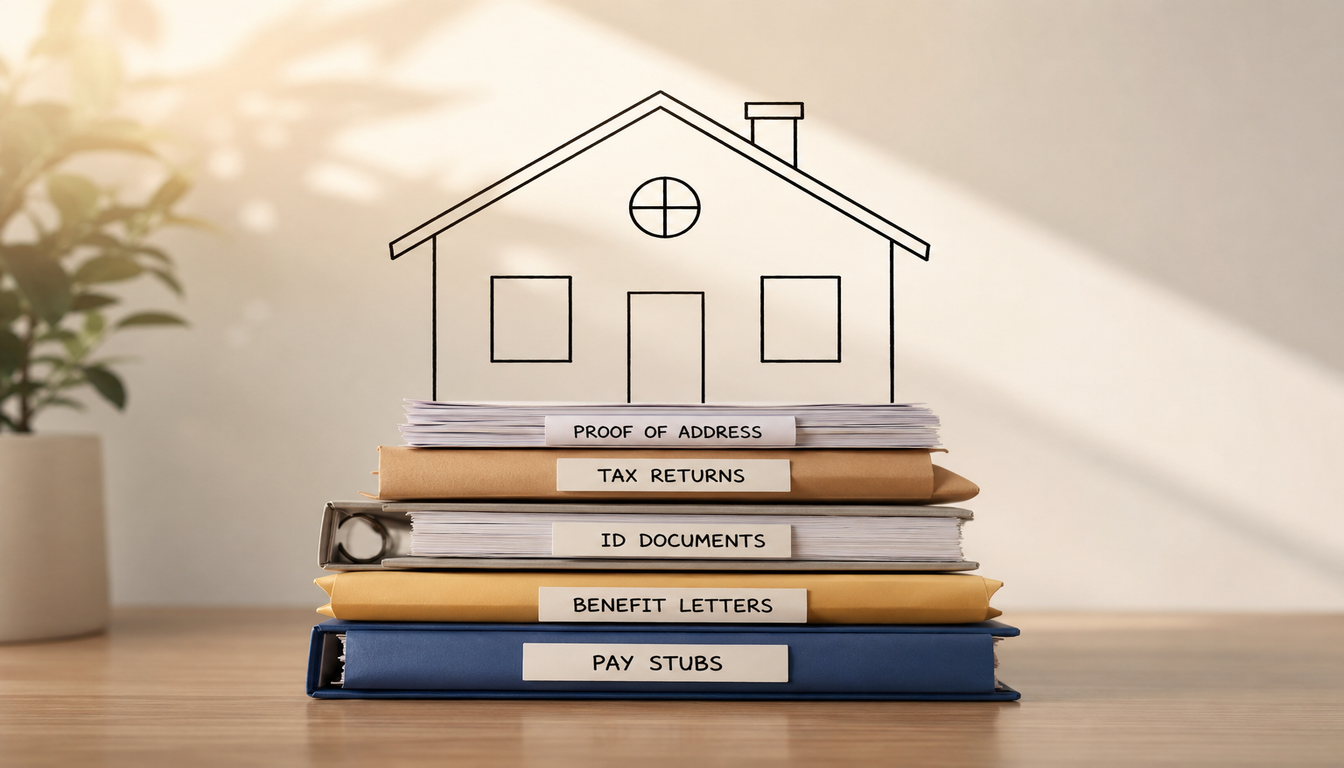
- Meet a minimum income. Under the federal regulations, this is generally the federal minimum wage times 2,000 hours, which comes to about $14,500 a year. For elderly or disabled families, the amount is based on the monthly SSI benefit. Some housing authorities set a higher number.
- Have steady work. At least one adult usually needs to work full time (an average of 30 hours a week) for at least a year. Elderly and disabled families are exempt.
- Complete a homebuyer class. This is required. The class covers mortgages, credit, and the costs of owning a home. Your housing authority will tell you which classes count, and you can also search for a HUD-approved housing counselor near you. Many classes are free or low cost.
- Get approved for a mortgage. You still have to qualify with a lender. Some housing authorities also set a credit score minimum, such as 620 for the head of household.
- Have no past mortgage default. If you failed to pay a mortgage backed by a HUD homeownership program, you may not qualify.
Get instant answers to your housing questions.Chat Now
What Does the Voucher Actually Pay For?
The voucher helps with your monthly costs, not the purchase itself. Eligible costs include your mortgage payment, mortgage insurance, property taxes, and homeowner's insurance. They also include allowances for utilities, routine upkeep, and major repairs. If you buy a condo or co-op, monthly association fees can count too.
Your share works much like it does with renting. What you pay is based on your income, and the voucher covers the rest, up to a limit your housing authority sets.
Does the Voucher Cover the Down Payment?
No, and this surprises many people. Voucher money cannot be used for the down payment or closing costs. HUD's rules mention a down payment grant option, but Congress has never funded it, so it does not exist in practice.
Some housing authorities also have their own savings rules. For example, one Iowa program asks buyers to put down 3% of the price, with at least 1% from the buyer's own money.
The good news is that other help is out there:
- State and local programs. Many states offer grants or low-interest loans for first-time buyers, and HUD's homebuying page points you to programs in your state. South Carolina, for instance, has a program made for voucher homeownership families that pairs FHA loans with forgivable down payment help.
- Family gifts. Lenders often let relatives give money toward a down payment with a signed gift letter.
- Savings programs. If you are in a Family Self-Sufficiency program, the savings you build there can go toward your purchase.
How Long Does the Help Last?
There is a time limit for most families. Help generally lasts up to 15 years if your mortgage runs 20 years or longer, and up to 10 years if the loan is shorter. Elderly and disabled households can get help for up to 30 years. When the limit ends, you keep the house and pay the mortgage yourself, so plan for that from day one.
Get instant answers to your housing questions.Chat Now
What Kind of Home Can You Buy?
Depending on the program, you may be able to buy a single-family house, a co-op, a condo, or a manufactured home. It must be your main home, and your housing authority will review the deal before you close.
Two inspections are usually required. First, the housing authority checks that the home meets basic safety and quality standards. It must pass before voucher help can begin. Second, you hire and pay for your own independent inspector. Don't skip this one, because an inspector can find problems like a bad roof or old wiring that could cost thousands to fix.
Get instant answers to your housing questions.Chat Now
Step-by-Step: How to Get Started
- Call your housing authority. Ask if it offers the program and what its rules are. You can look up your local housing authority on HUD's contact list.
- Check your income and work history against the requirements.
- Take a homebuyer class and keep your certificate.
- Work on your credit. Pay bills on time and pay down debt where you can. The Consumer Financial Protection Bureau's home buying guide walks you through loans, rates, and closing costs, so you can compare offers with confidence.
- Get pre-approved. Talk to a lender that works with the program. Your housing authority may have a list.
- Find a home and make an offer. Tell your housing authority before you sign anything.
- Complete both inspections and fix any problems before closing.
- Close on the home. Your monthly voucher help then goes toward your mortgage.
Rules After You Buy
Once you own the home, you have duties. Families sign a statement of homeowner obligations promising to live in the home, keep it in good shape, and report changes in income or family size. If you fall behind on payments, call your housing authority and lender right away. Many families get through a rough patch when they ask for help early.
Get instant answers to your housing questions.Chat Now
Is It Worth It?
For many families, yes. Owning can make your housing cost more stable over time, and you build equity as you pay down the loan. It has worked for many families. New York's state homeownership program, for example, has led to more than 750 home closings since it began as a small pilot in 2000.
But owning is not for everyone. You will face repair bills, taxes, and insurance that renters don't. Try to build an emergency fund before you buy.
Take the Next Step
The first step is simple: ask your housing authority what it offers. And if you are still searching for a voucher or want to explore affordable housing near you, visit our partner site, Section8Search.org, to look through listings and learn more about your options.